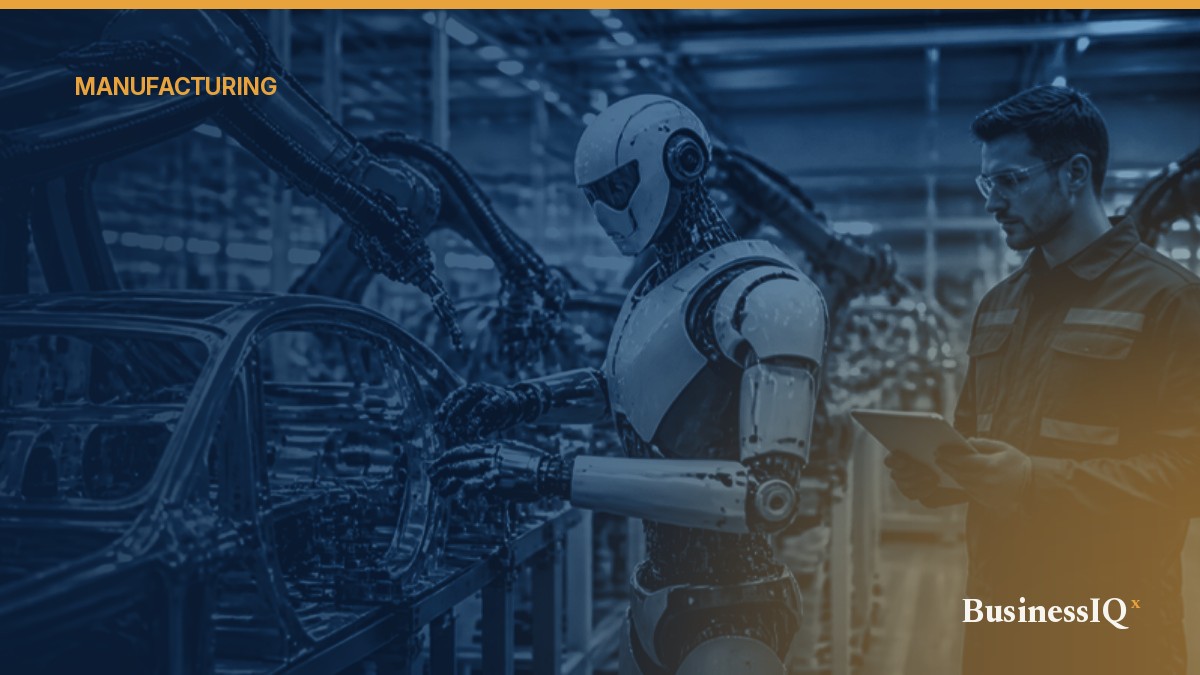

Walk through a modern car plant and the robots are everywhere, but they are also strangely limited. They weld, paint and lift with superhuman precision, bolted into cages and repeating the same motion thousands of times a shift. Change the product, move a part a few centimetres, or ask one to pick a tangled cable out of a bin, and they are helpless. The jobs that remain in manufacturing are mostly the ones that need hands, eyes and judgement working together.
That is the gap the latest wave of automation is trying to close. Engineers call it physical AI: the same family of models that learned to write text and code, now trained to see, grasp and move. The investment flowing into it has been enormous, from humanoid robot makers in California and Shenzhen to the foundation models from Nvidia and Google DeepMind that aim to give any robot a general-purpose brain. The question for manufacturers is which parts of this are ready to earn a return, and which are still a science project.
Where the Robots Are Today
The International Federation of Robotics’ World Robotics 2026 report, published in September, puts the scale of the shift in plain numbers. Factories installed around 603,000 industrial robots in 2025, up 11% on the year before, and the global operating stock passed five million units for the first time. China alone installed about 354,000, or 59% of the global total, and Chinese installations grew by around a fifth. Chinese brands now supply a majority of their home market.
The rest of the picture is uneven. The United States overtook Japan in 2025 to become the second largest market for new robots, helped by reshoring and the build-out of battery and semiconductor plants. The European Union went the other way, with installations falling sharply as its car industry cut investment. South Korea remains the most automated manufacturing economy on earth, with more than 1,000 robots for every 10,000 factory workers in the IFR’s density figures, several times the global average.
India barely registers on these tables. It installs a small fraction of China’s volume each year despite a fast-growing manufacturing base. As we argued in our piece on India’s manufacturing moment, that has been a deliberate trade-off in a labour-rich economy. It is one that may become harder to sustain as electronics and automotive supply chains demand the precision and consistency that automation delivers.
What Makes This Wave Different
Traditional industrial robots are programmed. An integrator writes every movement in advance, and the robot follows it exactly. That works brilliantly for high-volume, unchanging tasks, which is why cars and electronics account for so much of the installed base. It works badly for the long tail of manufacturing: short runs, many product variants and messy materials.
The new approach trains robots on huge amounts of video, simulation and human demonstration so that they can generalise. Show a model enough examples of picking up parts, and it can pick up a part it has never seen. Nvidia’s Isaac and GR00T platforms, Google DeepMind’s Gemini Robotics models and well-funded start-ups such as Physical Intelligence are all chasing the same prize: a robot that can be taught a new task in hours rather than reprogrammed over weeks.
Two other forces are pushing in the same direction. The first is labour. Manufacturers in the US, Germany, Japan and South Korea face shrinking pools of workers willing to do repetitive factory jobs, and China’s workforce is ageing faster than its economy is growing. The second is cost. Sensors, actuators and computing have become dramatically cheaper, and Chinese suppliers in particular have pushed down the price of robot hardware at a pace Western makers find hard to match.
Humanoids: Promise Versus the Payback Period
Humanoid robots get the headlines for an obvious reason. They are designed to work in spaces built for people, using the same tools, stairs and workstations, without the factory being rebuilt around them. Figure AI has run pilots with BMW at its Spartanburg plant in South Carolina. Agility Robotics’ Digit has moved totes in GXO warehouses under a robots-as-a-service contract. Hyundai has said it will deploy Boston Dynamics’ Atlas at its new Georgia plant, and Tesla keeps promising Optimus for its own lines. In China, UBTech, Unitree and a crowd of newer firms have placed humanoids in car and electronics factories run by BYD, Zeekr and Foxconn.
The honest assessment is that most of these deployments are still pilots. Humanoids today are slower than skilled workers, need frequent charging and supervision, and struggle with the reliability that a production line demands. A robot that succeeds 95% of the time sounds impressive until you realise it fails dozens of times a shift. The business case improves sharply if prices fall towards the tens of thousands of dollars that several makers are targeting, but that depends on volumes that do not yet exist.
None of this means humanoids are hype. It means they are early. A sensible manufacturer should watch them closely and perhaps run a pilot, while recognising that the money being made from physical AI in 2026 is mostly coming from less glamorous machines.
| Robot type | Typical installed cost | Best suited to | Typical payback |
|---|---|---|---|
| Traditional industrial arm | $100,000 to $400,000 including integration | Welding, painting, heavy handling, high volume | 1.5 to 3 years at high utilisation |
| Collaborative robot (cobot) | $30,000 to $80,000 including tooling | Machine tending, packing, screwdriving, small batches | Under 18 months in many SMEs |
| Autonomous mobile robot | $30,000 to $100,000 per unit plus software | Moving parts and goods between stations | 1 to 2 years |
| AI vision and picking cell | $150,000 to $500,000 | Bin picking, sorting, inspection of varied parts | 2 to 3 years |
| Humanoid robot | Often leased, pricing still unsettled | General handling in spaces built for people | Unproven outside pilots |
These ranges are broad and vary heavily by region, labour cost and shift pattern, but the pattern they show is consistent. The fastest returns come from flexible, modest machines that slot into existing lines, not from replacing a whole worker with a mechanical copy of one.
The Quiet Winners: Cobots, Vision and Mobile Robots
Collaborative robots, or cobots, are the most practical way for a mid-sized manufacturer to start. They are light, can work alongside people without cages, and can be set up by a technician rather than a specialist integrator. A plant making 50 product variants a month would never justify a traditional robot cell for most of them. A cobot that can be moved and retaught in an afternoon changes that arithmetic.
AI-driven vision is where physical AI is already paying for itself most clearly. Systems that inspect welds, spot surface defects or pick mixed parts from a bin have improved enormously as the underlying models have got better. Quality inspection in particular offers a double return: fewer people on tedious checking, and fewer defective products reaching customers. Autonomous mobile robots that move materials around a factory floor are the third quiet success, borrowed from warehouse logistics and now spreading into production.
Automation and the Reshoring Decision
The most important strategic effect of physical AI may be on where things get made. For decades, the logic of offshoring rested on cheap labour. If robots can handle a growing share of assembly and handling, labour cost matters less, and other factors matter more: proximity to customers, energy prices, tariffs, political risk and the speed of getting a new product to market.
That is why automation keeps appearing in the reshoring plans we discussed in our coverage of supply chain sovereignty and China plus one. A battery plant in Georgia or a chip packaging site in Arizona only works economically because it is far more automated than the equivalent plant would have been 20 years ago. The irony is that China itself is automating faster than anyone, which means the cost advantage that Western reshoring hopes to close is a moving target.
There is a geopolitical layer too. Many robot components, from precision reducers to motors that depend on rare earth magnets, are now supplied by Chinese firms. A Western manufacturer that automates to reduce its dependence on Chinese labour may find it has swapped it for a dependence on Chinese robot parts. Procurement teams should map that exposure before it becomes a problem.
The Workforce Question
Every wave of automation brings predictions of mass unemployment, and every wave so far has instead changed what factory work looks like. The evidence from countries with the highest robot density is instructive. South Korea, Germany and Japan have kept substantial manufacturing employment while automating heavily, because the productivity gains helped them stay competitive.
What does change is the mix of skills. Plants need fewer people doing repetitive handling and more people who can maintain robots, interpret data, run quality systems and solve problems when something stops. The bottleneck at many firms is not robot supply but technicians. The companies getting the best returns treat retraining as part of the automation budget, and involve shop floor staff in deciding which tasks to automate first. Workers usually know exactly which jobs are dangerous, boring or error-prone, and those are often the best places to start.
A Practical Playbook for Manufacturers
Start with the problem, not the robot. Map the tasks that cause the most injuries, defects or staffing headaches, and rank them by how repetitive and predictable they are. The best first projects are tasks that are dull, measurable and currently done by people who would rather be doing something else.
Measure payback honestly. Include integration, training, maintenance, downtime during installation and the cost of the floor space. Many automation projects fail not because the robot does not work but because the business case assumed it would run three shifts at full speed from day one.
Prefer flexibility over peak performance. In a world of shorter product cycles and unpredictable tariffs, a robot that can be redeployed is worth more than one that is optimal for a single job. Finally, keep a small budget for experiments with newer AI-driven systems, including humanoids, so that the organisation learns what they can do before competitors do.
The Factory of the Next Decade
The fully dark factory, running without people and without lights, remains rare and is likely to stay that way for most products. What is arriving instead is a factory where robots handle a far larger share of the physical work, AI watches every step for quality, and a smaller, more skilled workforce spends its time on the things machines still cannot do.
The manufacturers that thrive will be those that treat automation as a capability to be built over years rather than a product to be bought. The robots are getting smarter quickly. The organisations that use them need to keep up.
